Strategy statistics answer one question: is this setup still earning money after costs, and how confident can you be about it? Account P&L cannot tell you that, because it mixes every strategy, every impulsive trade and every experiment into one number.
This page shows how to calculate the two core numbers, expectancy and profit factor, with worked examples. It then covers the checks that stop an average from fooling you: sample size, drawdown, streaks and where the profit actually came from.
Check the data before the numbers
Statistics are only as clean as the tagging behind them. Before you read any metric, confirm the strategy has a written definition, each trade carries one primary tag, P&L is net of charges and only closed trades are counted.
Then look at the trade count. A win rate measured over 10 trades can be off by about 31 percentage points either way. At 100 trades that margin narrows to about 10 points.
Expectancy: what one trade is worth
Expectancy is the average result per trade. If you took the same setup a hundred more times under the same conditions, it is roughly what each attempt would add to or take from your account.
To express it in R, divide by the amount you risk per trade. If this strategy risks ₹2,000 on each trade, ₹570 is about +0.29R. R makes strategies of different sizes comparable, and the example below shows why win rate alone is misleading.
Strategy A feels better to trade because it wins most days. It still loses money, since 0.7 × 1R is 0.7R and 0.3 × 3R is 0.9R. The same payoff shape can appear in short option selling, or in scalps where the stop keeps getting moved.
Profit factor: how wins stack against losses
Below 1.0, the strategy loses money. As a rule of thumb, many intraday setups sit between 1.2 and 1.8 after costs. If you see a profit factor above 2.0 on a small sample, open the trade list and check whether one expiry day or one trending session produced most of it.
Look past the averages
Expectancy and profit factor are averages, and averages hide the shape of the results. Two strategies can both show ₹570 per trade while one grinds steadily and the other depends on a single ₹40,000 winner.
- Max drawdown as a percentage of the capital given to the strategy. This is the pain you need to sit through to earn the expectancy.
- Longest losing streak. Ask whether you could survive it again at your current size.
- Largest single loss. One gap opening on a short straddle can set the month's drawdown.
- Share of net P&L from the top one or two symbols or days.
- Results by session. Some edges exist only in the first 45 minutes after the 9:15 open.
Drawdown also changes which strategy is better for you. In an illustrative pair, strategy C earns ₹400 per trade with a worst drawdown of ₹18,000, and strategy D earns ₹900 per trade with a worst drawdown of ₹45,000. D makes more per trade, but if your account or your nerves cannot sit through a ₹45,000 dip, C is the one you will actually keep trading.
A five-loss streak on its own does not prove an edge has gone. Losing streaks happen even in strategies with positive expectancy. Check whether the rules were followed on those trades before you change anything.
Reading strategy statistics in TradeLyser
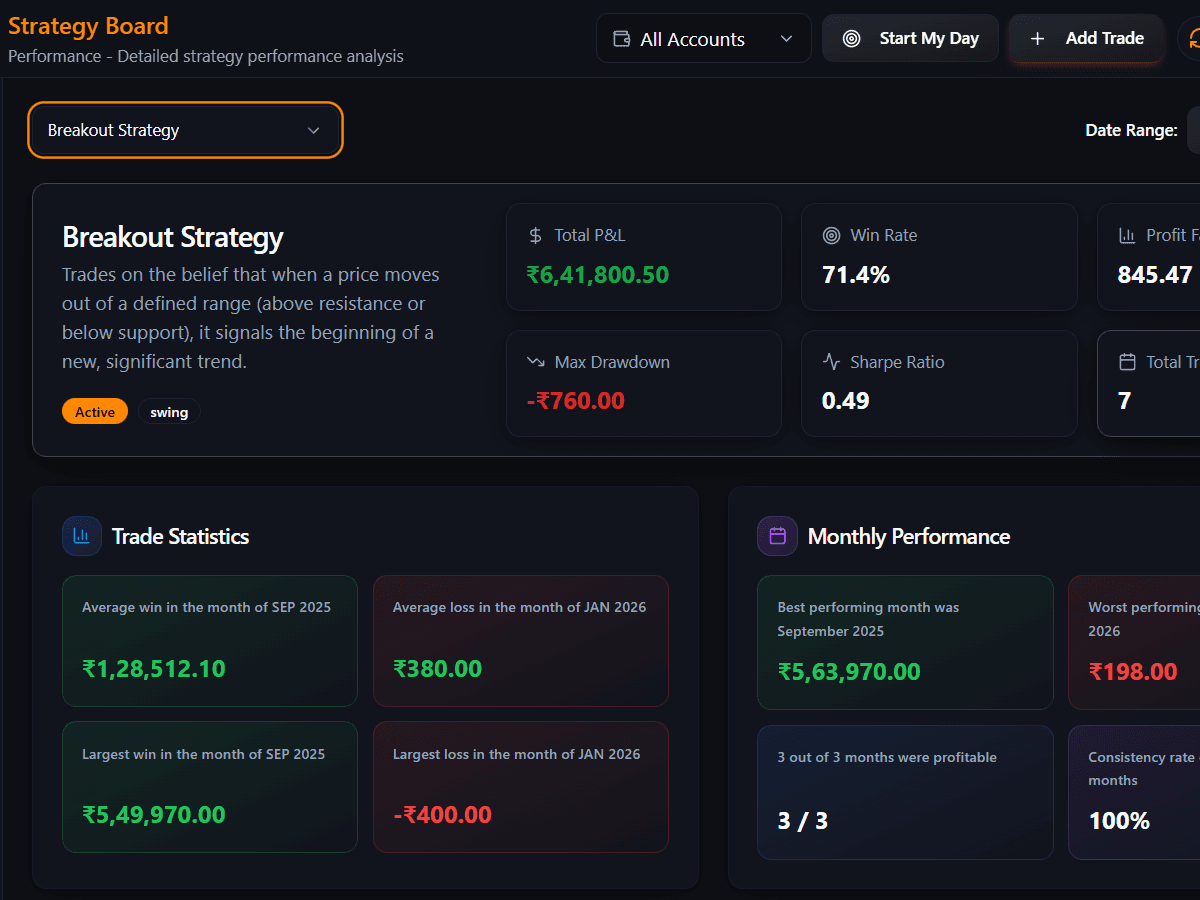
- Open Strategy Lab and select one strategy.
- Check the trade count first. If it is under 30, read everything else as provisional.
- Read win rate together with profit factor and max drawdown, not on its own.
- Scan the monthly performance for one month that carries the whole result.
- Write one line in your weekly review: keep, research or pause, and why.
The same page shows a Sharpe ratio, which compares return with how much the returns swing from period to period. It is most useful for comparing a strategy with its own earlier months. A falling Sharpe with steady expectancy usually means results have become lumpier, which is worth a look at position size.
Questions traders ask
What is the most important metric for a trading strategy?
Expectancy per trade after costs, because it tells you what each trade is worth on average. Read it together with profit factor and max drawdown for the same window, and with the number of trades behind it.
What is a good profit factor for an intraday strategy?
Anything below 1.0 loses money. As a rule of thumb, many intraday strategies sit somewhere between 1.2 and 1.8 after costs. A figure above 2.0 on a small sample usually means one or two big trades are carrying the result.
How do I calculate expectancy for my trades?
Multiply your win rate by your average win, then subtract your loss rate multiplied by your average loss. Use net figures after brokerage and taxes, and only closed trades from one strategy.