Most active traders run more than one setup. An opening range breakout in the morning, a VWAP trade around midday, a few expiry-day scalps when the mood strikes. Without a fair way to compare them, money drifts towards whichever one paid last fortnight.
This page covers how to set up a comparison so the numbers mean something, which four figures to put side by side, and how to turn the result into a written decision for each strategy.
Set up a fair comparison first
A comparison is only as good as the data behind it. Two strategies measured over different months, or one measured before charges and one after, will give you a ranking that has nothing to do with skill.
- Use the same calendar window for every strategy, for example the last 90 days.
- Count closed trades only. Open positions change the numbers every tick.
- Use net P&L after brokerage, STT, exchange charges and GST.
- Give each trade one primary strategy tag. If a trade could fit two, write down the rule you use to pick one.
- Note any date where you changed the rules or the size of a strategy.
Each strategy should also be defined clearly enough that you could explain it to another trader in half a minute: instrument, session window, entry, exit and maximum risk per trade. If two setups share an entry but exit differently, treat them as two strategies.
The four numbers to put side by side
You can compare strategies on dozens of metrics. Four of them answer the questions that matter: does it make money per trade, can you trust that figure, how much pain does it cause, and how do the wins stack up against the losses.
| Metric | What it answers | Rule of thumb | Watch for |
|---|---|---|---|
| Expectancy | Average result per trade, in R or rupees, after costs | Must be above zero to keep trading live | A high win rate with negative expectancy |
| Sample size | How much the other numbers can be trusted | 30+ closed trades; 100+ for options or swing | Rankings built on 10 or 15 trades |
| Max drawdown | The deepest fall from a peak, as % of allocated capital | Within the limit you wrote before trading it | Two strategies with equal P&L but very different dips |
| Profit factor | Gross profit divided by gross loss | Below 1.0 is losing money | Values above 2.0 on a small sample, usually one outlier week |
Win rate is missing from that table on purpose. It is useful context, but a 70% win rate with losses three times the size of wins still loses money. Read it next to average win and average loss, never alone.
Use R where you can. R is the amount you planned to risk on a trade, so a ₹50,000 scalping strategy and a ₹5,00,000 swing strategy land on the same scale. Rupee expectancy works when both strategies risk roughly the same amount per trade.
Worked example: three intraday strategies
Here is an illustrative case. A trader tags three intraday strategies on Nifty and Bank Nifty and compares them over the same 90 days, after charges.
The opening range breakout has the best expectancy and the largest sample, so it is the easiest call. The VWAP reclaim is positive, but 41 trades is only just past the minimum and +0.11R is small enough that a few trades could flip it. The expiry-day scalps have a decent sample and lose about a fifth of an R every time they are taken.
Opening range breakout
VWAP reclaim
Expiry-day scalps
Drawdown then decides how much capital each one gets. Suppose the opening range breakout fell 7% from its peak at worst, about ₹14,000 on a ₹2,00,000 allocation, against a written limit of 10%. It stays at normal size. Had it dropped 15% on the way to the same +0.32R, you would keep the strategy but trade it smaller until you understood that dip.
How to run the comparison in TradeLyser
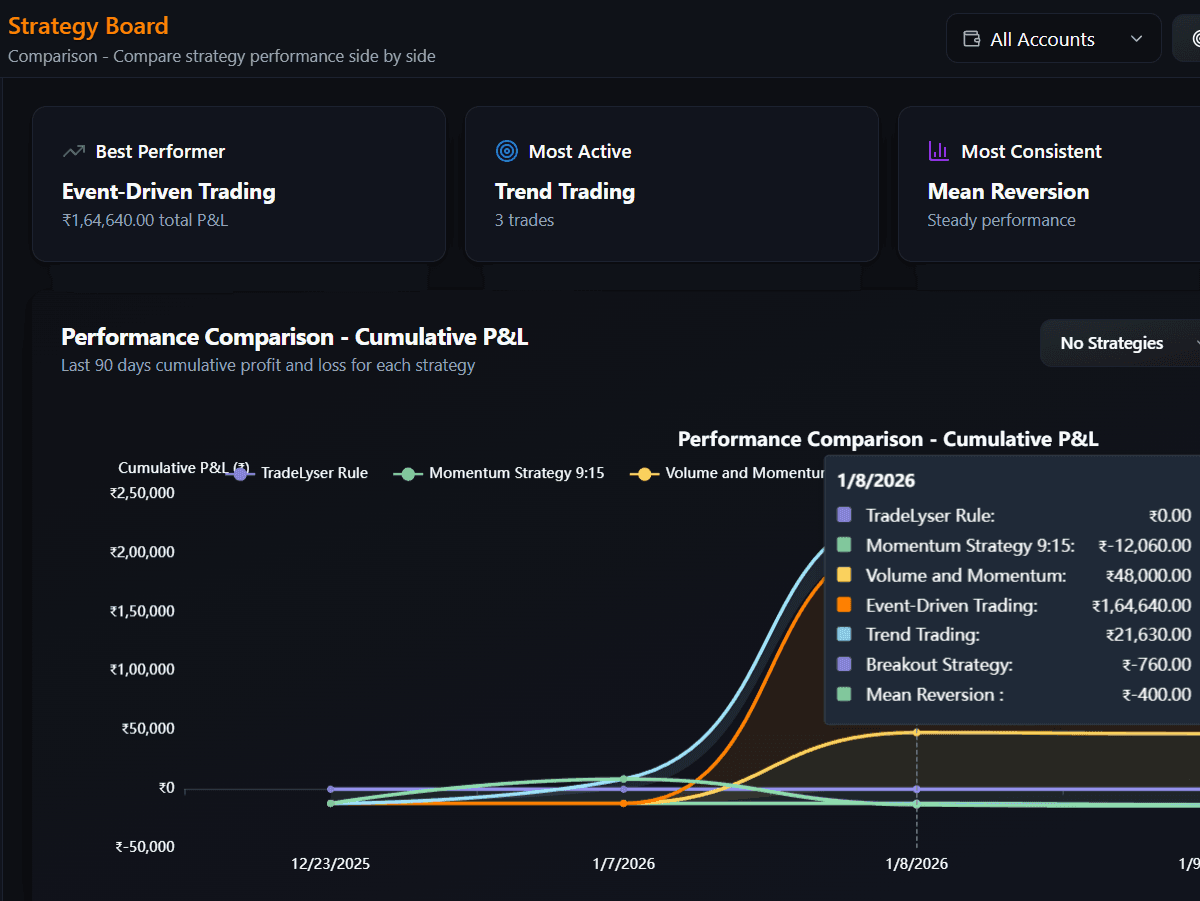
- Create each strategy in Strategy Lab and tag trades to it going forward, one primary tag per trade.
- Open the comparison view and set the same date range for every strategy.
- Note trade count, net P&L, expectancy, profit factor and max drawdown for each one.
- Look at the cumulative P&L lines. A steady climb and a single jump can end at the same number.
- Write keep, research or pause next to each strategy before the next session.
The "best performer" card is a starting point for questions. Before acting on it, check the trade count behind it and whether one or two trades produced most of the gain.
Comparison mistakes to avoid
- Comparing strategies over different date ranges, so one gets a trending month and the other gets chop.
- Blending iron condors, short straddles and long options under one "options" tag. Each structure has its own risk profile.
- Mixing backtest or paper trades with live trades in the same strategy.
- Changing size halfway through the window without noting the date.
- Promoting a strategy to full size after one strong week.
Questions traders ask
How many trades do I need before comparing two trading strategies?
As a rule of thumb, at least 30 closed trades per strategy, and 100 or more for options structures or slow swing setups. Below 30, one good or bad week can reverse the ranking.
Is win rate a good way to compare trading strategies?
Not on its own. A strategy that wins 70% of the time can still lose money if its losses are much larger than its wins. Compare expectancy first and read win rate together with average win and average loss.
Can one trade belong to two strategies when comparing?
Only if you have a written rule for it, and in most cases it is better to pick one primary tag per trade. If a trade counts in two strategies, both trade counts are inflated and the comparison is unreliable.